


Related insights
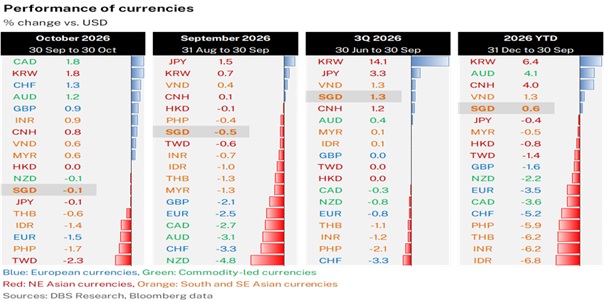
The DXY Index slipped back below 102 again after the October 28 FOMC meeting. The committee voted 10-2 to maintain the Fed Funds Rate at 3.75-4.00%, with both dissenters favouring a 25-bps hike. Although the FOMC statement retained a hawkish bias, Fed Chairman Kevin Warsh’s reluctance to endorse a December hike tempered its impact. Subsequent US GDP and PCE inflation releases did little to restore the USD’s momentum.
The US midterm elections on November 3 and nonfarm payrolls on November 6 will test whether the USD’s loss of momentum extends. The US Treasury 10-year yield retreated below 5% towards 4.90%, as the equity sell-off drove demand for safety. Concerns over cash burn at AI hyperscalers sharpened scrutiny of the investment boom underpinning the US exceptionalism narrative. Stronger headline GDP growth offered limited reassurance about households’ ability to withstand high fuel prices and mortgage rates. A Democratic sweep at the midterms could compound the above risks by increasing the likelihood of legislative gridlock, fiscal confrontation, and a renewed government shutdown.
The USD’s lost momentum does not automatically create a compelling case for the EUR. Europe’s fiscal and political uncertainties, particularly in France, and its vulnerability to elevated energy prices complicate the search for viable alternatives. Nonetheless, the EUR did find support from the European Central Bank providing clearer guidance than the Fed on the prospects of a December hike and Moody’s affirmation of France’s Aa3 sovereign debt rating.
GBP has emerged as a more resilient alternative to the EUR. The October 28 UK Autumn Budget did not unsettle the gilt market and market pricing for an interest rate hike at the November 5 Bank of England meeting. Following the 6-3 vote supporting the September 17 pause, the vote split will likely be 7-2 this Thursday, with more MPC members acknowledging growing inflation risks.
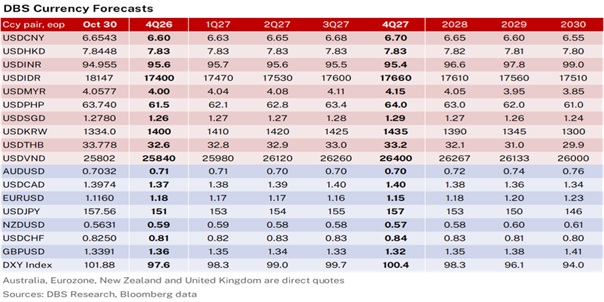
The AUD has largely priced in a 25-bps hike to 4.85% at the November 3 Reserve Bank of Australia meeting. CPI inflation did accelerate to 4.3% YoY from 4% in August, in line with the RBA’s warning. Although the three earlier hikes appear to be cooling the labour market, weak productivity growth continues to sustain inflationary pressures despite subdued consumption growth.
The RBA could, nevertheless, disappoint by following the Reserve Bank of New Zealand’s surprise pause or by delivering a hike while signalling that rates are nearing peak. The RBA’s accompanying Statement on Monetary Policy will likely show 2027 forecasts revised lower for GDP growth and higher for inflation, underscoring the RBA’s difficult policy trade-off. AUD/USD’s recovery from 0.6894 to 0.7032 in the second half of October remains tentative, with the USD also likely to determine if it can break last week’s peak at 0.7068.
Quote of the Day
“We must accept finite disappointment, but never lose infinite hope.”
Martin Luther King, Jr.
Today in history
President Ronald Reagan signed legislation to create a federal holiday honouring Martin Luther King, Jr. in the Rose Garden of the White House on November 2, 1983.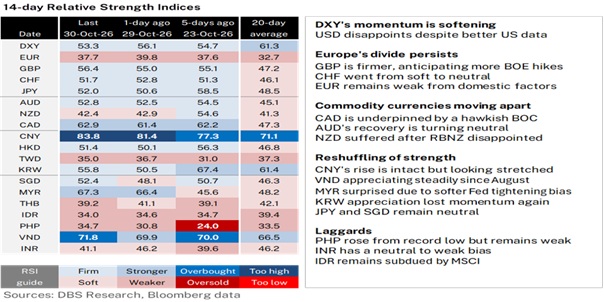

Topic
GENERAL DISCLOSURE/ DISCLAIMER (For Macroeconomics, Currencies, Interest Rates, Digital Assets or Commodities)[1]
The information herein is published by DBS Bank Ltd and/or DBS Bank (Hong Kong) Limited (each and/or collectively, the “Company”). It is based on information obtained from sources believed to be reliable, but the Company does not make any representation or warranty, express or implied, as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions expressed are subject to change without notice. This research is prepared for general circulation. Any recommendation contained herein does not have regard to the specific investment objectives, financial situation and the particular needs of any specific addressee. The information herein is published for the information of addressees only and is not to be taken in substitution for the exercise of judgement by addressees, who should obtain separate legal or financial advice. The Company, or any of its related companies or any individuals connected with the group accepts no liability for any direct, special, indirect, consequential, incidental damages or any other loss or damages of any kind arising from any use of the information herein (including any error, omission or misstatement herein, negligent or otherwise) or further communication thereof, even if the Company or any other person has been advised of the possibility thereof. The information herein is not to be construed as an offer or a solicitation of an offer to buy or sell any securities, futures, options or other financial instruments or to provide any investment advice or services. The Company and its associates, their directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned herein and may also perform or seek to perform broking, investment banking and other banking or financial services for these companies. The information herein is not directed to, or intended for distribution to or use by, any person or entity that is a citizen or resident of or located in any locality, state, country, or other jurisdiction (including but not limited to citizens or residents of the United States of America) where such distribution, publication, availability or use would be contrary to law or regulation. The information is not an offer to sell or the solicitation of an offer to buy any security in any jurisdiction (including but not limited to the United States of America) where such an offer or solicitation would be contrary to law or regulation.
[#for Distribution in Singapore] This report is distributed in Singapore by DBS Bank Ltd (Company Regn. No. 196800306E) which is Exempt Financial Advisers as defined in the Financial Advisers Act and regulated by the Monetary Authority of Singapore. DBS Bank Ltd may distribute reports produced by its respective foreign entities, affiliates or other foreign research houses pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed in Singapore to a person who is not an Accredited Investor, Expert Investor or an Institutional Investor, DBS Bank Ltd accepts legal responsibility for the contents of the report to such persons only to the extent required by law. Singapore recipients should contact DBS Bank Ltd at 65-6878-8888 for matters arising from, or in connection with the report.
DBS Bank Ltd., 12 Marina Boulevard, Marina Bay Financial Centre Tower 3, Singapore 018982. Tel: 65-6878-8888. Company Registration No. 196800306E.
DBS Bank Ltd., Hong Kong Branch, a company incorporated in Singapore with limited liability. 18th Floor, The Center, 99 Queen’s Road Central, Central, Hong Kong SAR.
DBS Bank (Hong Kong) Limited, a company incorporated in Hong Kong with limited liability. 11th Floor, The Center, 99 Queen’s Road Central, Central, Hong Kong SAR.
[1] This disclaimer may not apply if the applicable assets fall within the definition of 'financial instruments' that are set out in Article 2(1) EU MAR (e.g. financial instruments that are traded on a regulated market, MTF or OTF, etc.). Section C of Annex I of MiFID2 specifies these 'financial instruments'.
Related insights
Related insights

- Member of Central Deposit Insurance Corporation (CDIC)